How to File Income Tax Returns Easily and Avoid Common Mistakes
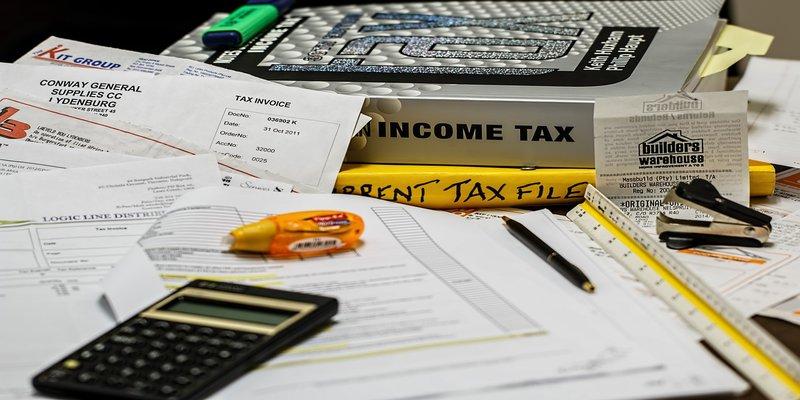
Filing income tax returns is an essential financial responsibility for individuals, professionals, and business owners. Although the process may seem complicated at first, understanding the requirements and following a systematic approach can make it much easier. Proper income tax filing helps you meet legal obligations, maintain accurate financial records, and avoid unnecessary penalties. Whether you are filing for the first time or managing your taxes every year, knowing the right steps can save time, reduce stress, and improve your financial planning. In this guide, you will learn how to file income tax returns easily, prepare the necessary documents, and avoid common mistakes that may create problems in the future.
What Is Income Tax and Why Is Filing Important?
Income tax is a tax imposed by the government on taxable income earned by individuals, businesses, and other eligible entities. The amount payable depends on applicable tax laws, income sources, allowable deductions, and other relevant factors. Filing an income tax return involves reporting your income and other required financial information to the relevant tax authority.
Timely filing is important because it helps taxpayers comply with legal requirements and maintain a transparent financial record. Depending on local regulations, an accurate tax return may also support financial transactions, business activities, loan applications, and other administrative processes. In Pakistan, taxpayers generally use the Federal Board of Revenue (FBR) and its online services to complete applicable income tax filing procedures.
Step 1: Gather the Required Documents
The first step toward easy income tax filing is collecting all necessary documents before beginning the process. Having the correct information available helps prevent errors and reduces the likelihood of submitting an incomplete return.
Essential Documents for Income Tax Filing
Depending on your circumstances, you may need the following documents:
Valid CNIC or other applicable identification details.
Salary certificates, payslips, or employer-issued income statements.
Bank statements and information about profit or other taxable income.
Business income records, invoices, and expense details.
Records of rental income, investments, or other income sources.
Details of tax deducted or collected at source.
Supporting documents for eligible deductions, credits, or tax adjustments.
Information about assets, liabilities, and other financial details where required.
Review these documents carefully before filing. Accurate records make it easier to calculate taxable income and respond to questions from the relevant tax authority if necessary.
Step 2: Understand Your Taxable Income
Understanding your total income is one of the most important parts of filing an income tax return. Taxable income may include salary, business profits, rental earnings, investment returns, and other income depending on the applicable law.
Start by identifying every relevant income source for the tax year. Next, calculate the amounts accurately and determine which expenses, deductions, exemptions, or credits are permitted under the applicable tax rules. Do not assume that every expense is deductible or that all income is treated identically.
For salaried individuals, employer statements and withholding tax records can help verify earnings and tax already paid. Business owners should maintain organized accounts that distinguish business revenue from personal transactions. If you have multiple income sources, consider professional assistance to ensure that your income tax calculations reflect the correct requirements.
Step 3: Use the Appropriate Online Tax Filing System
Many tax authorities provide online platforms that allow eligible taxpayers to submit returns electronically. In Pakistan, the FBR's online tax system, commonly known as IRIS, is used for relevant registration and filing services.
To begin, access the official FBR website and sign in to the appropriate account. If you are a new taxpayer, check the current registration requirements and complete any necessary steps before proceeding. Select the relevant tax year and return form, then enter your personal information, income details, tax deductions, and other required information.
Follow the instructions displayed by the platform and review each section before submitting your return. Requirements and forms may change, so always consult current official guidance rather than relying entirely on older tutorials or unofficial advice.
Step 4: Calculate Tax Payable or Refunds
After entering your financial information, review the tax calculation carefully. Your final liability may depend on applicable tax rates, taxable income, withholding tax, eligible credits, and other adjustments.
Compare the calculated tax with the amount already deducted or paid during the tax year. If you have paid more than your final liability, you may qualify for a refund under the relevant rules. If additional tax is due, follow the official payment instructions and ensure that the payment is properly recorded.
Never enter estimated figures simply to complete the form quickly. Use reliable documentation and verify calculations before submission. When your financial circumstances are complex, a qualified tax professional can help identify errors and explain available legal options.
Common Income Tax Filing Mistakes to Avoid
Even small errors can cause delays, incorrect tax calculations, or compliance problems. Understanding common mistakes can help you submit a more accurate return.
1. Reporting Incomplete Income
One frequent mistake is forgetting income from a secondary job, rental property, investment, or business activity. Review all relevant financial records to ensure that required income is reported correctly.
2. Entering Incorrect Personal Information
Incorrect identification details, bank information, contact information, or tax-year selections can create unnecessary complications. Double-check every entry before submitting the return.
3. Claiming Unverified Deductions
Some taxpayers claim expenses or tax benefits without confirming eligibility. Only include deductions, exemptions, or credits supported by applicable law and appropriate documentation.
4. Ignoring Withholding Tax Records
Failing to report tax already deducted or paid may result in an inaccurate calculation. Compare withholding certificates, bank records, and other available evidence before finalizing your return.
5. Missing Filing Deadlines
Late filing can lead to penalties or other consequences, depending on the applicable rules. Check the official deadline for the relevant tax year and submit your return in advance whenever possible.
6. Submitting Without a Final Review
Rushing through the process can lead to missing information and inconsistent figures. Review your return thoroughly and save copies of the submitted documents and acknowledgment.
Practical Tips for Making Income Tax Filing Easier
You can simplify future income tax filing by developing a consistent recordkeeping routine. Maintain a dedicated folder for receipts, income statements, bank records, and tax payment confirmations. Updating these records throughout the year is easier than collecting everything shortly before a deadline.
Use spreadsheets or reliable accounting software to track income and expenses where appropriate. Keep copies of previous returns to help identify recurring information, but do not automatically repeat old figures without verifying them. Set calendar reminders for important filing and payment dates, and check official announcements for changes in tax regulations.
If you are unsure about a particular tax treatment, consult a qualified tax adviser familiar with your circumstances and jurisdiction. Professional guidance can be especially valuable for business owners, freelancers, property investors, and individuals with income from multiple countries.
Benefits of Accurate and Timely Income Tax Filing
Filing your income tax return correctly offers several practical advantages. It helps demonstrate compliance with applicable tax laws, supports organized financial management, and reduces the risk of avoidable errors and penalties. Accurate records may also be useful when applying for financing, conducting business transactions, or completing other financial procedures, although requirements vary by institution and jurisdiction.
For businesses, proper tax compliance contributes to stronger accounting practices and more informed financial decisions. For individuals, it provides a clearer picture of income, tax payments, and financial obligations. Most importantly, consistent filing habits help you approach tax season with greater confidence and fewer last-minute difficulties.
Conclusion
Filing income tax returns does not have to be stressful. By organizing your documents, understanding your taxable income, using the correct filing platform, verifying calculations, and meeting deadlines, you can make the process more manageable and avoid common mistakes. Careful recordkeeping and a final review are essential for accurate reporting and better financial planning. Whether you are an individual taxpayer or a business owner, staying informed about current tax requirements can help you fulfill your responsibilities efficiently. When your situation involves complicated income sources or uncertain tax rules, seeking professional advice can provide additional clarity and confidence.
Join the Conversation
Share Your Thoughts
Related Articles
How Business Formation Lawyers in Pakistan, UAE and Saudi Arabia Help
Starting a business in a new market can be an exciting opportunity, but it also comes with legal responsibilities, regulatory requirements,
How to Choose Intellectual Property Lawyers in Pakistan, UAE and Saudi Arabia
Benefits of Business Formation Lawyers in Pakistan, UAE and Saudi Arabia
Starting a business is an important milestone for entrepreneurs, investors, and established companies looking to expand into new markets.